
Condo insurance • Michigan
Condo Master Policy Coverage: How Your Bylaws Impact Your Insurance
Match your unit policy to the association’s actual repair responsibilities.
Read the documents
Check unit boundaries
Estimate Coverage A
Review assessments
The short answer
Condo master policy coverage varies by association. Read the declaration and bylaws alongside the master policy to learn which parts of your unit the association insures and which repairs belong to you. Then set your HO-6 dwelling (Coverage A), personal property and loss assessment limits to match those responsibilities.
Why It Matters
A condo owner can have a personal policy and still face a large bill after a covered fire or water loss. The association policy might repair common elements but leave unit finishes, improvements, or a share of the master deductible to the owner. A generic dwelling limit may miss that exposure. Paying to insure original finishes already covered by the association can also duplicate protection, though policy terms must be compared carefully.
In Michigan, obtain current association documents and insurance information, including deductibles and amendments. Ask who repairs damaged property, who insures it, and whether the association may assess an owner. Answers can differ by cause of loss.
How Master Policies Draw the Boundary
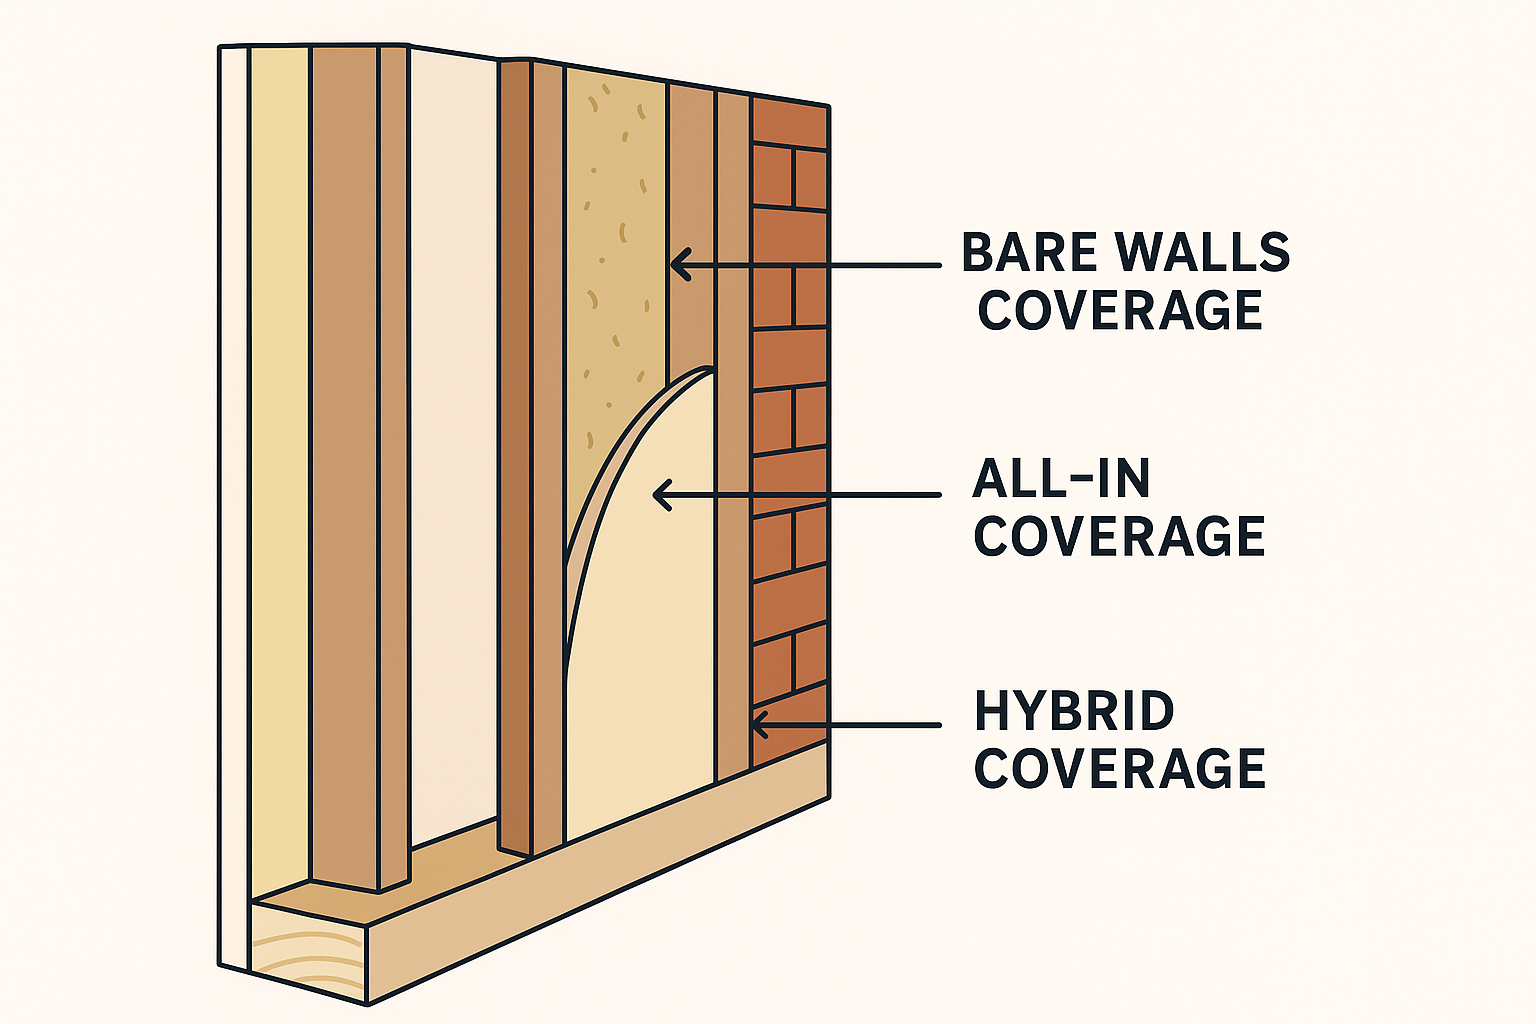
Bare walls or studs out
The association often insures the structure and common areas while the unit owner insures more of the interior. The precise boundary can include or exclude drywall, fixtures and built-ins; the label alone is insufficient.
Single entity or all in
Some master policies insure original construction and fixtures but leave later improvements and betterments to the owner. “All in” does not mean every personal possession or liability exposure is covered.
Modified or hybrid
Associations may allocate drywall, paint, cabinets, plumbing fixtures and flooring in different ways. Read the actual documents instead of assuming one standard arrangement. Resolve differences between the governing documents and insurance contract before selecting limits.
Set the Right HO-6 Limits
List the interior building items you must restore: walls, cabinets, flooring, counters, fixtures, appliances and upgrades. Estimate the cost to rebuild your responsibility at current local labor and material prices, not a flat dollar range based on policy labels. That informs Coverage A. Separately inventory personal property and review replacement cost terms, additional living expense and liability.
Deductibles and loss assessment
Ask whether a master deductible can be charged to one unit or assessed among owners. Loss assessment coverage may help with certain covered assessments, but triggers, per-occurrence limits, special deductibles and exclusions matter. It does not guarantee payment for maintenance, ordinary capital projects or every uninsured association loss.
For home policy basics, see the Michigan Department of Insurance and Financial Services. Our replacement cost versus actual cash value guide explains valuation.
What to Bring to a Review
- Current declaration, bylaws and amendments.
- Master policy summary or certificate, deductible schedule and loss assessment rules.
- Details and approximate replacement costs for upgrades and betterments.
- Your HO-6 declarations, endorsements and personal property inventory.
Ask the association for missing documents. An agent can compare your policy with those terms; the association or legal counsel can clarify governing-document obligations.
Frequently Asked Questions
Does the master policy cover everything inside my condo?
Usually not. Coverage depends on association documents and the policy. Personal belongings and personal liability generally require your own policy.
Does an all-in policy mean I need no dwelling coverage?
No. Improvements, betterments, gaps and other owner responsibilities may still require Coverage A.
Will loss assessment coverage pay every special assessment?
No. It generally applies only to qualifying covered losses subject to limits and exclusions. Routine maintenance is different.
Can I use the same limit as another owner?
Units and upgrades differ. Base your limit on your responsibilities and replacement costs.
Review Your Condo Coverage
Customers First Insurance Group can compare association documents with your HO-6 policy and discuss limits. Contact our team or request a quote.
Disclaimer: General insurance education, not legal advice or a coverage determination. Association documents, insurer forms, endorsements, deductibles and claim facts control. Consult your association and a licensed insurance professional.